
Founders granting stock options and investors reviewing a cap table both run into the same question sooner or later. What is this company’s stock actually worth, and can that number survive scrutiny from the IRS? A 409a valuation answers exactly that, and it shapes everything from an employee’s tax bill to how confidently an investor can evaluate a deal during due diligence.
A lot of confusion around this topic comes from mixing up a company’s headline funding valuation with the separate, IRS-driven number used for equity compensation. In this article, we’ll define what a 409a valuation is, explain when a company needs one, walk through how it gets calculated, and show why it matters so much for fundraising and due diligence. We’ll also touch on cost, timeline, and how a strong valuation history strengthens a company’s standing with serious capital.
By the end, you’ll have a clear, practical grasp of the topic, whether you’re a founder preparing to grant options or an investor reading a data room. Let’s get into the details.
Key Takeaways
A 409a valuation is an independent, third-party assessment of a private company’s common stock, required under Section 409A of the Internal Revenue Code.
Companies need one before granting the first stock options, then must refresh it annually or after major events like funding rounds.
Appraisers rely on three IRS-recognized methods, the market approach, the income approach, and the asset approach, often blended together.
A clean 409a history signals financial discipline and is a real marker investors check during due diligence.
The valuation typically lands below the price paid in a preferred funding round, and it directly affects both tax exposure and exit planning.
What Is A 409a Valuation
A 409a valuation is an independent, third-party assessment of the fair market value of a private company’s common stock, named after Section 409A of the Internal Revenue Code. It’s not something a founder or finance team can simply estimate internally, it has to come from a qualified outside appraiser who has no financial stake in the outcome.
This number becomes the baseline exercise price for stock options and other equity awards granted to employees and service providers. When a company grants options at or above this fair market value, employees are shielded from immediate tax exposure, and the company gains protection against the pitfalls of IRC 409A that come with undervaluing equity. Without this documented benchmark, both sides carry unnecessary tax risk that a properly timed valuation is designed to prevent.
Why Does A 409a Valuation Matter For Founders And Investors
A 409a valuation matters because it protects founders from compliance risk while giving investors a documented signal of how seriously a company handles its financial governance. For founders, getting this right isn’t just a box to check, it directly affects whether employees face surprise tax bills down the road and whether the company’s equity practices hold up under scrutiny during a future raise or acquisition. A company that treats its valuation as an afterthought often finds that sloppy documentation surfaces at the worst possible moment, usually right when a bigger investor or acquirer starts asking pointed questions about the cap table.
On the investor side, a company’s 409a history deserves the same attention as its financial statements, since it offers a window into whether management runs a tight ship. A current, well-documented valuation shows that founders understand tax law, respect their employees’ financial interests, and have likely built other governance habits worth seeing before capital gets committed. When that documentation is missing, outdated, or clearly rushed, it raises a flag that usually leads to more questions rather than fewer.
How Monaco Business Angels Views 409a Compliance During Due Diligence
Monaco Business Angels treats 409a compliance as one of many signals weighed when vetting deal flow before it reaches the investor network. The due diligence process looks closely at cap table accuracy and equity documentation, because founders who get this right tend to handle other financial responsibilities with the same rigor. Founders seeking capital raising support through this network benefit from showing this discipline early, since it speeds up conversations with sophisticated investors.
When Do Companies Need A 409a Valuation
Companies need a 409a valuation before they grant their very first stock option, and then on a regular refresh schedule after that. This timing question trips up a lot of first-time founders who assume they can wait until after a funding round closes, but the IRS requirement kicks in the moment equity compensation enters the picture, often right around initial hiring or a seed round.
Beyond that first valuation, companies generally need to update the number annually or whenever a material event changes the business meaningfully. A Series A or Series B round almost always triggers a refresh, since new investor pricing reshapes the picture. Other triggers include:
A major pivot in business model or strategy
A significant swing in financial performance
A material shift in competitive position
Any of these can make a stale valuation legally and practically indefensible.
How Is A 409a Valuation Calculated
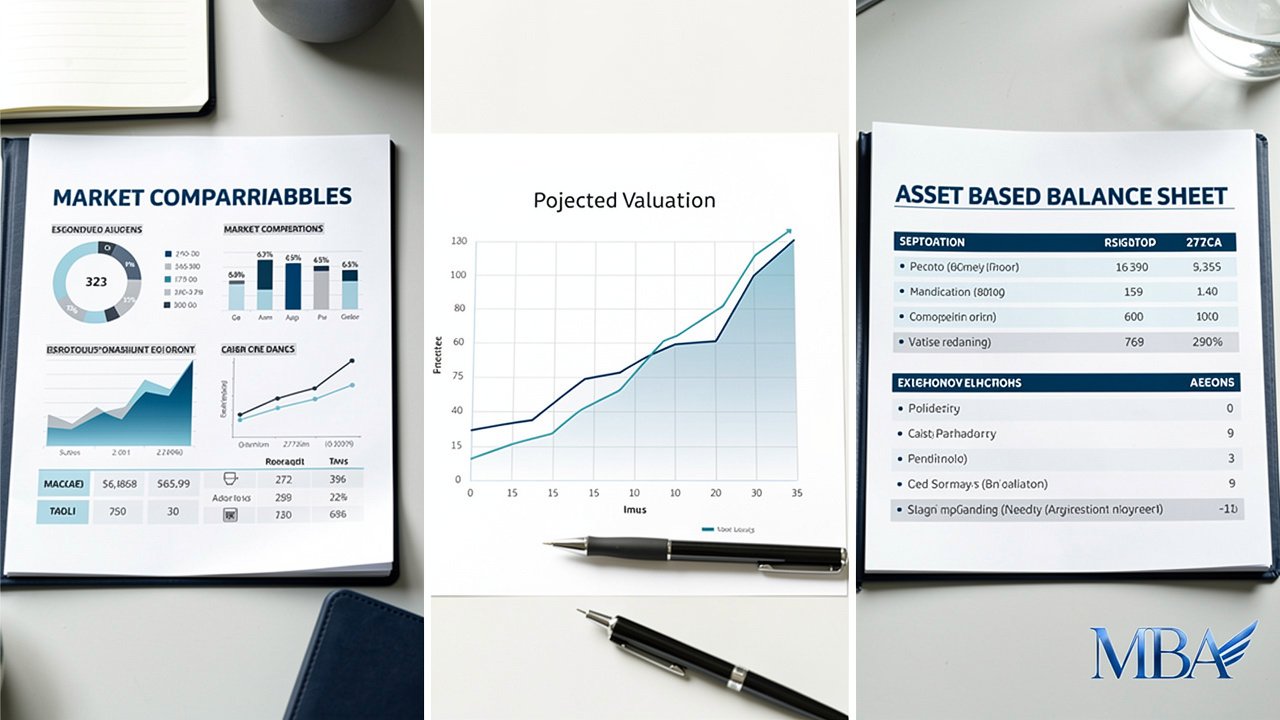
A 409a valuation gets calculated using one or more of three IRS-recognized methods, following a step-by-step valuation process that appraisers apply based on the company’s stage, industry, and available financial data. Qualified appraisers rarely rely on a single method in isolation, instead they blend approaches to triangulate a number that holds up to scrutiny from auditors, investors, and the IRS alike. An early-stage company with no revenue history will lean on different inputs than a growth-stage business with several years of predictable cash flow, and a good appraiser adjusts the weighting of each method accordingly. Understanding these three approaches helps founders and investors interpret why a given valuation looks the way it does.
Market Approach
The market approach compares the company to similar public or private businesses using metrics like revenue or EBITDA multiples. This method works well once there’s enough comparable transaction data available, though very early-stage companies sometimes lack close enough comparables to make it fully reliable on its own.
Income Approach
The income approach projects the company’s future cash flows and discounts them back to today’s value. It suits businesses with predictable revenue streams, since it depends heavily on assumptions about growth rates and an appropriate discount rate reflecting company risk.
Asset Approach
The asset approach values the company based on its tangible and intangible assets minus liabilities. It matters most for asset-heavy businesses like real estate or manufacturing, and it’s typically far less relevant for software or tech startups with minimal physical assets.
How Do Funding Rounds Affect 409a Valuation
Funding rounds affect a 409a valuation because the price investors pay for preferred stock becomes an important reference point, though it’s never a direct substitute for the common stock number. When a company closes a preferred financing round, appraisers use that pricing as a strong data point, but they adjust it downward to account for the extra rights preferred shareholders receive, things like liquidation preferences and participation rights that common stockholders don’t get.
This is why investors and founders should expect the 409a valuation to land below the price paid per preferred share in the same round, sometimes well below it. That gap isn’t a red flag on its own, it reflects the real difference in rights between preferred and common stock. Understanding this distinction matters for anyone reading a term sheet next to a valuation report, since confusing the two numbers leads to misplaced assumptions about what employee equity is actually worth.
What Do 409a Valuations Cost And How Long Do They Take
A 409a valuation typically costs between $1,500 and $5,000 for early-stage companies, with the price climbing for more complex capital structures or larger businesses. The exact figure depends on how much financial data the company already has organized, the industry it operates in, and how many valuation methods the appraiser needs to apply to reach a defensible conclusion.
Timelines usually run two to four weeks from the start of the engagement to the final report, though this can move faster if the company arrives with clean, organized financials and a clear cap table. Annual refresh valuations often cost less than the first one, since the appraiser already understands the business, though a refresh following a major funding round or performance shift may require more work than a routine update. Founders who plan for this timeline ahead of a hiring push or funding close avoid scrambling at the last minute.
The Takeaway
A current, well-documented 409a valuation protects everyone at the table, the founders granting equity, the employees receiving it, and the investors evaluating the company’s overall financial discipline. It’s a small piece of paperwork with outsized consequences, since getting it wrong can mean unexpected tax bills for employees or red flags for investors during due diligence.
This same disciplined, evidence-based mindset is exactly what Monaco Business Angels brings to connecting vetted founders with sophisticated private capital across Monaco, Europe, and international markets. Whether you’re a founder preparing your equity documentation for your next raise or an investor looking for verified deal flow across technology, real estate, and other alternative assets, it’s worth exploring what the network has to offer.
Frequently Asked Questions
Can A Company Avoid Getting A 409a Valuation
No, any company issuing stock options needs one to establish a compliant exercise price and avoid tax penalties. There’s no exemption based on company size or funding stage once equity compensation enters the picture, so founders should plan for this requirement from the very first option grant.
Who Is Qualified To Perform A 409a Valuation
Independent, credentialed appraisers, such as those holding ASA, CVA, or CFA designations, with no financial stake in the company are qualified to perform this work. Using a conflicted advisor, like an investment banker tied to a pending financing, weakens the IRS safe harbor protection the valuation is meant to provide.
What Happens If A 409a Valuation Is Too Low
If a valuation is set too low, the IRS may treat the undervalued options as immediate taxable compensation. That triggers back taxes, a 20% penalty, and accrued interest for the affected employees, a scenario detailed in guidance on plan contribution timing requirements and how such tax delays get corrected.
Does Every Funding Round Trigger A New 409a Valuation
Not automatically, but most institutional rounds from Series A onward materially change the company’s fair value. In practice, these rounds typically require a refreshed 409a valuation to keep the exercise price aligned with the company’s new financial reality.
How Does A 409a Valuation Differ From A Company’s Overall Valuation In A Funding Round
A 409a valuation prices common stock specifically for tax purposes, while a funding round valuation reflects preferred stock pricing negotiated with investors. Preferred stock carries extra rights like liquidation preferences, which is why the two numbers rarely match.
What Documentation Should Investors Request When Reviewing A Company’s 409a History
Investors should ask for the full valuation report, the methodology the appraiser used, confirmation of the appraiser’s independence, and the date of the last update relative to recent funding or major business changes. This paints a clear picture of how seriously the company treats its equity compliance obligations.